Home Loans
All Loan ProgramsFirst Time BuyersConventional LoansFHA LoansVA LoansJumbo LoansDSCR Investor LoansBank Statement LoansFirst Time Home Buyer in Arizona: Programs, Costs and Steps
A first time buyer in Arizona needs a credit score that fits the loan, cash to close and a pre approval. Most buy with 0 to 3.5% down through FHA, conventional 97, HomeReady, Home Possible, VA or USDA. Pillar Mortgage Group, a Scottsdale broker, compares them across multiple lenders and closes in 18 days on average.
Quick facts: buying your first home in Arizona (verified October 26, 2026)
- Lowest down payments: VA and USDA 0% for eligible buyers, FHA 3.5% with a 580 or higher score, and 3% on conventional 97, HomeReady and Home Possible.
- 2026 FHA limits for a one unit home: $557,750 in Maricopa and Pinal counties, $609,500 in Coconino County and $541,287 in every other Arizona county (HUD).
- 2026 conforming loan limit: $832,750 for a one unit home in every Arizona county (FHFA).
- A first time buyer generally means no ownership interest in a home during the past 3 years (Fannie Mae).
- FHA's 1.75% upfront premium can be financed, and its annual premium ends after 11 years only if you start at 90% loan to value or less (HUD).
- Pillar Mortgage Group closes in 18 days on average, and as fast as 10.
Sources: HUD FHA limits, FHFA, Fannie Mae, HUD ML 2023-05. Full list in the Sources section below.
What a first time buyer in Arizona needs
You need four things lined up: a credit score that meets your loan program, enough cash for the down payment and closing costs, income that supports the payment, and a pre approval from a lender. HomeReady adds a fifth item when every borrower is a first time buyer: a homeownership education course.
- Credit. FHA allows 3.5% down at 580. Fannie Mae sets no minimum through its automated system and 620 for manually underwritten fixed rate loans.
- Cash. 0% down on VA and USDA, 3% on conventional 97, HomeReady and Home Possible, 3.5% on FHA, plus closing costs.
- Income. Lenders compare your monthly debts with your income. See our guide to debt to income ratio in Arizona.
- Pre approval. Get it before you tour homes. How pre approval works with PMG.
Arizona first time buyer loan programs compared
Start with the traditional low down payment loans. These are the options most Arizona first time buyers use, checked against each official source on October 26, 2026. Credit scores are listed only where the program itself states one.
| Program | Minimum down | Minimum credit | Income limit | Key rule | Source |
|---|---|---|---|---|---|
| FHA | 3.5% with a 580+ score; 10% with 500 to 579 | 580 for 3.5% down; 500 floor | None | Primary residence. 1.75% upfront premium plus an annual premium (0.55% on most 30 year loans under 5% down) | HUD Handbook 4000.1 HUD ML 2023-05 |
| Conventional 97 | 3% | No set minimum through Fannie Mae's automated system; 620 if manually underwritten (fixed rate) | None on the standard 97% option | On the standard 97% option at least one borrower must be a first time buyer. PMI above 80% loan to value, removable later | Fannie Mae 97% LTV FAQs Fannie Mae B3-5.1-01 |
| HomeReady (Fannie Mae) | 3% | Not set on the program page | 80% of area median income | Open to first time and repeat buyers. Education required when every borrower is a first time buyer | Fannie Mae HomeReady Fannie Mae B5-6-01 |
| Home Possible (Freddie Mac) | 3% (97% LTV) | Not set on the program page | 80% of area median income | Fixed 3% down with flexible sources of funds | Freddie Mac Home Possible |
| VA | 0% in most cases | VA sets none; lenders set their own | None | Certificate of Eligibility. No monthly mortgage insurance. Funding fee 2.15% on first use under 5% down, waived for veterans receiving disability compensation | VA loan limits VA funding fee |
| USDA | 0% (100% financing) | Not set on the program page | 115% of median household income | Home must be in an eligible rural area. FY 2027 fees: 1.00% upfront, 0.35% annual | USDA Rural Development USDA FY 2027 fees |
Checked October 26, 2026. Program rules change, so confirm before you rely on them. Not a commitment to lend. Also see all loan programs, FHA loan limits in Arizona and 2026 conventional loan limits.
Free: The 2026 Arizona First Time Home Buyer Checklist
The order we walk our own clients through, with the Arizona specific steps most national guides skip. Fill out the short form and the PDF is yours right away.
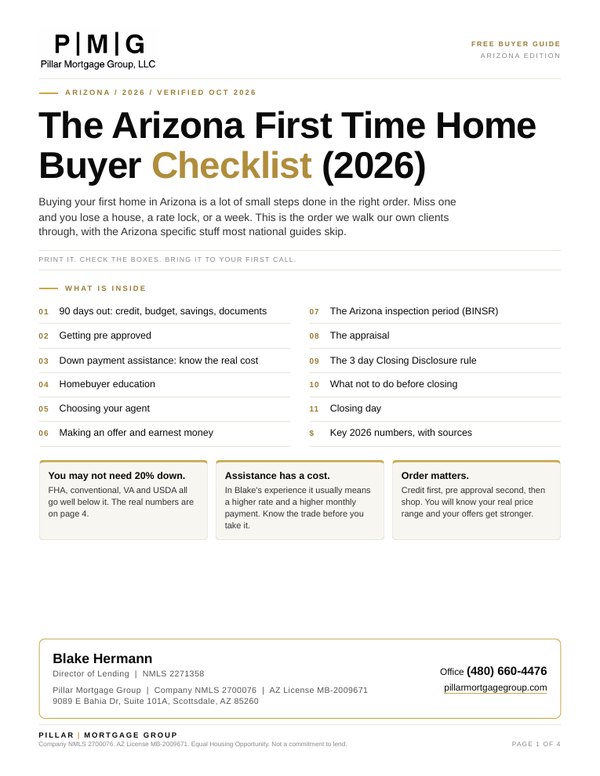
- 11 steps in order, from 90 days out to closing day
- Arizona specifics: the inspection period and BINSR, the appraisal and the 3 day Closing Disclosure rule
- Key 2026 numbers with their official sources
- Built to use: print it, check the boxes, bring it to your first call
Send Me the Free Checklist
No commitment · Under 2 minutes
You're all set!
Your checklist is below, and a member of our team will reach out shortly with your first time buyer plan.
Down payment assistance: know the real cost
Arizona has assistance programs, and they can make sense for some buyers who are short on cash. Most are a second loan rather than a grant, several carry income limits, and some must be repaid if you sell or refinance early. If you are curious, here is what is available as of October 26, 2026:
- HOME Plus (Arizona IDA, statewide): up to 4% as a 0% second lien, forgiven after 60 months and repaid if you sell or refinance sooner; 620 score; income up to $155,386. The Arizona IDA says its first mortgage rates "may be slightly higher than current industry rates." (Arizona IDA HOME Plus, HOME Plus income limits)
- Home in Five Advantage (Maricopa County): up to 6%; 640 score; income up to $153,440. (Home in Five Advantage)
- City of Phoenix Open Doors: up to 10% of the price for first time buyers in Phoenix city limits; income at or below 80% of area median income; price up to $470,250. (City of Phoenix)
- Tucson and Pima County HOME DPA: up to $50,000 or 20% of price, whichever is less; principal repaid when you sell. (Tucson and Pima County fact sheet)
- Arizona Is Home: closed for the rest of 2026 as of October 6, 2026. (Arizona IDA notice)
Pillar Mortgage Group does not run any of these programs. If you want to see one, we will price the same home with and without it so you can compare the payment. More detail: Arizona down payment assistance programs and their tradeoffs.
What to do first: your Arizona first time buyer checklist
Work through these steps in order. The first five happen before you write an offer.
- Check your creditPull your free reports at AnnualCreditReport.com and fix errors before you apply. FHA allows 3.5% down with a 580 score, and a higher score usually means better conventional pricing.Source: AnnualCreditReport.com
- Set a budget from the monthly paymentStart from the payment you are comfortable with, not the list price. Include principal, interest, property tax, insurance, HOA dues and mortgage insurance. The cost to buy calculator on this page does the math.Open the calculator
- Get pre approvedA pre approval checks your income, assets and credit before you shop, so sellers take your offer seriously. Pillar Mortgage Group can issue most pre approvals the same day.How pre approval works
- Know the real cost of down payment assistanceIf you are looking at assistance, get the rate and payment with it and without it. Blake's take: down payment assistance usually carries a higher rate, so your payment is often higher than a traditional loan. Compare both before you choose.Arizona DPA programs and their tradeoffs
- Take homebuyer education if your loan requires itHomeReady requires a homeownership course when every borrower is a first time buyer. Fannie Mae's HomeView course meets that rule, and it is useful even when it is optional.Source: Fannie Mae HomeReady
- Choose a buyer's agentPick an agent who knows your target area and how your loan type works. Share your pre approval so they search in the right price range.
- Make an offer and deposit earnest moneyYour agent writes the offer on the Arizona purchase contract. Once it is accepted you deposit earnest money with escrow, which counts toward your cash to close.Earnest money in Arizona
- Use your inspection period and the BINSRHire an inspector right away. During the inspection period you can ask the seller for repairs or credits on the Buyer's Inspection Notice and Seller's Response, or cancel under the contract terms.Inspection period and BINSR
- Get the appraisal and finish underwritingThe lender orders the appraisal and verifies your file. Answer document requests quickly and do not open new credit or move money without asking first.FHA property standards
- Review your Closing DisclosureYour lender must give you the Closing Disclosure at least three business days before you close. Compare it with your Loan Estimate and ask about every change.The 3 day rule explained · Source: CFPB
- Sign, fund and get your keysYou sign with escrow, the loan funds and the deed records. Pillar Mortgage Group's average close is 18 days, and as fast as 10.What not to do before closing
- Want all 11 steps on one page?Get the printable checklist with the key 2026 numbers and their sources.Get the free checklist
Arizona Cost to Buy Calculator
Estimate your cash to close and monthly payment. Every dollar figure comes from what you enter plus the published federal fee rates listed under the results. Your numbers stay in your browser unless you choose to email them.
Your cost to buy estimate
Enter a price and your quoted rate to see your cash to close and monthly payment.
How this is calculated
Base loan = price minus down payment. Payment = loan × r × (1 + r)^360 ÷ ((1 + r)^360 minus 1), where r = rate ÷ 12.
FHA: 1.75% upfront premium added to the loan; annual premium of 0.50% (loan to value 95% or less) or 0.55% (above 95%) on base loans up to $726,200, and 0.70% or 0.75% above that, shown as a first year monthly estimate. Source: HUD Mortgagee Letter 2023-05.
VA: funding fee added to the loan. First use 2.15% under 5% down, 1.5% at 5% or more, 1.25% at 10% or more; after first use 3.3% under 5% down. Source: VA.gov.
USDA: 1.00% upfront guarantee fee added to the loan and 0.35% annual fee, shown as a first year monthly estimate. Source: USDA Rural Development, FY 2027.
Cash to close = down payment + closing costs minus assistance and credits. Earnest money you deposit counts toward it.
Email me my breakdown
We will send these numbers to you and follow up to help you compare programs.
By submitting you authorize Pillar Mortgage Group LLC to contact you by phone, text, or email. Your information is never sold.
Estimates only. Not a loan offer or a commitment to lend. Rates, fees and program rules vary by lender, property and borrower. Company NMLS #2700076.
First time buyer loan options by Arizona city
The loan rules are the same statewide, but the FHA limit changes by county. That limit decides how much home you can buy with 3.5% down on FHA. Above it, a 3% down conventional loan up to $832,750 is the usual next step. VA works anywhere with full entitlement, and USDA depends on the exact address, so check it on the USDA eligibility map.
First time buyers in Phoenix
Maricopa County
- 2026 FHA limit, one unit: $557,750
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Scottsdale
Maricopa County
- 2026 FHA limit, one unit: $557,750
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Mesa
Maricopa County
- 2026 FHA limit, one unit: $557,750
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Gilbert
Maricopa County
- 2026 FHA limit, one unit: $557,750
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Chandler
Maricopa County
- 2026 FHA limit, one unit: $557,750
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Tucson
Pima County
- 2026 FHA limit, one unit: $541,287
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
First time buyers in Flagstaff
Coconino County
- 2026 FHA limit, one unit: $609,500
- 2026 conforming limit, one unit: $832,750
- Above the conforming limit you need a jumbo loan
Buying somewhere else in Arizona?
The same loan programs work statewide. Tell us the address and we will check the county limit and your options.
Book a free callWhy use a broker as a first time buyer
A bank offers its own programs. Pillar Mortgage Group is a broker, so we compare FHA, conventional, VA and USDA options across multiple wholesale lenders, and show you the cash to close and payment for each side by side. Broker vs bank vs direct lender.
How it works with PMG
Your loan is led by Blake Hermann, Director of Lending and Arizona first time homebuyer expert (NMLS 2271358).
- Tell us your goal.Use a form on this page or call the office at (480) 660-4476, Monday to Friday 9 to 5 and Saturday 10 to 2.
- Get pre approved.We review your credit, income and assets and tell you which loans fit.
- Compare your options.We price FHA, conventional, VA and USDA side by side across multiple lenders.
- Close.Our average close is 18 days, and as fast as 10, with updates at every step.
Go deeper
Short guides to the questions first time buyers ask us most.
First time home buyer FAQ
Straight answers to what first time buyers ask us most. Still have a question? Talk to a real person.
Book a free callSources
All sources accessed October 26, 2026. Pillar Mortgage Group facts (office line, hours, average close, licensing) come from Pillar Mortgage Group.
- HUD FHA Mortgage Limits lookup, FHA Forward, Arizona, CY2026: https://entp.hud.gov/idapp/html/hicostlook.cfm
- HUD No. 25-145, 2026 FHA loan limits announcement, December 11, 2025: https://hud.gov/news/hud-no-25-145
- HUD Handbook 4000.1, FHA Single Family Housing Policy Handbook: https://www.hud.gov/hud-partners/single-family-handbook-4000-1
- HUD Mortgagee Letter 2023-05, FHA annual and upfront mortgage insurance premiums: https://www.hud.gov/sites/dfiles/OCHCO/documents/2023-05hsgml.pdf
- FHFA, Conforming Loan Limit Values for 2026, November 25, 2025: https://www.fhfa.gov/news/news-release/fhfa-announces-conforming-loan-limit-values-for-2026
- Fannie Mae Selling Guide glossary, first time homebuyer definition: https://guide-selling.fanniemae.com/first-time-homebuyer
- Fannie Mae Selling Guide B3-5.1-01, General Requirements for Credit Scores: https://selling-guide.fanniemae.com/sel/b3-5.1-01/general-requirements-credit-scores
- Fannie Mae, 97% LTV Options FAQs: https://singlefamily.fanniemae.com/learning-center/originating-and-underwriting/faqs-97-ltv-options
- Fannie Mae, HomeReady Mortgage: https://singlefamily.fanniemae.com/originating-underwriting/mortgage-products/homeready-mortgage
- Fannie Mae Selling Guide B5-6-01, HomeReady Mortgage Loan and Borrower Eligibility: https://selling-guide.fanniemae.com/sel/b5-6-01/homeready-mortgage-loan-and-borrower-eligibility
- Freddie Mac, Home Possible: https://sf.freddiemac.com/working-with-us/origination-underwriting/mortgage-products/home-possible
- VA, VA home loan limits (last updated August 12, 2025): https://www.va.gov/housing-assistance/home-loans/loan-limits/
- VA, Funding fee and closing costs (last updated October 5, 2026): https://www.va.gov/housing-assistance/home-loans/funding-fee-and-closing-costs/
- USDA Rural Development, Single Family Housing Guaranteed Loan Program: https://www.rd.usda.gov/programs-services/single-family-housing-programs/single-family-housing-guaranteed-loan-program
- USDA Rural Development bulletin, FY 2027 guarantee fees, September 16, 2026: https://content.govdelivery.com/accounts/USDARD/bulletins/42b1054
- USDA Income and Property Eligibility Site: https://eligibility.sc.egov.usda.gov/eligibility/welcomeAction.do
- Arizona IDA, HOME Plus Down Payment Assistance: https://homeplusaz.com/home-plus-dpa/
- Arizona IDA, HOME Plus 2026 income limits: https://homeplusaz.com/homeplus-2026-income-limits/
- Arizona IDA, Arizona Is Home status notice, October 6, 2026: https://homeplusaz.com/arizona-is-home-dpa/
- Home in Five Advantage, Maricopa County: https://www.homein5advantage.com/
- City of Phoenix, Homeownership Opportunities (Open Doors): https://www.phoenix.gov/administration/departments/housing/housing-options/homeownership-opportunities.html
- City of Tucson and Pima County, Down Payment Assistance fact sheet, updated June 2026: https://www.tucsonaz.gov/files/sharedassets/public/v/7/living-and-working/housing-community-development/documents/dpa-fact-sheet-english-4.20.2026-final-version.pdf
- Fannie Mae Servicing Guide B-8.1-04, Termination of Conventional Mortgage Insurance: https://servicing-guide.fanniemae.com/svc/b-8.1-04/termination-conventional-mortgage-insurance
- CFPB, What is a Closing Disclosure?: https://www.consumerfinance.gov/ask-cfpb/what-is-a-closing-disclosure-en-1983/
- AnnualCreditReport.com, free credit reports: https://www.annualcreditreport.com/
- First American Title, Homebuyer's guide to closing costs in Arizona (rates on transactions closed on or after April 1, 2024): https://info.firstam.com/homebuyers-guide-to-closing-costs-in-arizona
Get your first time buyer plan.
Tell us where you want to buy and when. We will check the loan options that fit, and lay out your cash to close before you make an offer.
Submit the form and you also get our free Arizona First Time Home Buyer Checklist as a PDF download.
Get My First Time Buyer Plan
No commitment · Under 2 minutes
You're all set!
A member of our team will reach out shortly with your first time buyer plan.
Pillar Mortgage Group, LLC is an Equal Housing Lender, doing business in accordance with the Fair Housing Act and Equal Credit Opportunity Act. Not a commitment to lend. Down payment assistance programs are run by their administrators, not by Pillar Mortgage Group.
Company NMLS# 2700076 | Arizona License MB-2009671 | View NMLS Consumer Access